 Back Home
Free Home-Buyer Clinic presented by Royce Kemp Realtor
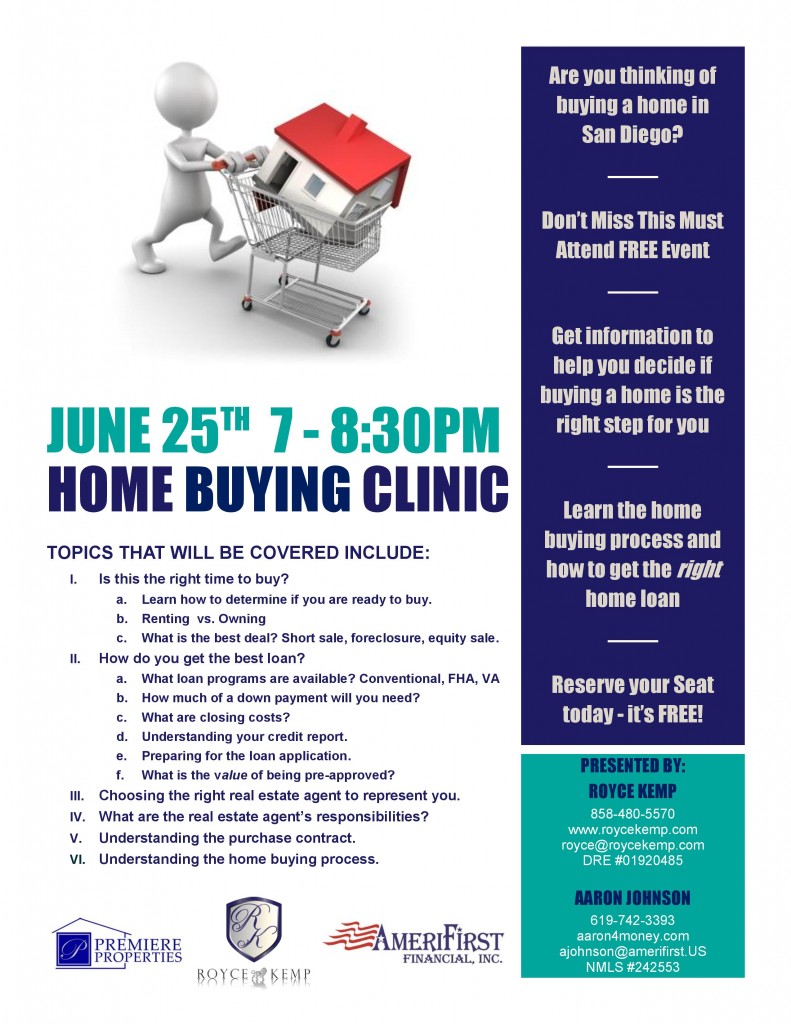
Royce Kemp Realtor co-hosts a Free Home-Buyer Clinic
Did You Know?
Your mortgage lender may run a second credit report just prior to closing. Red flags that appear in this credit report can disqualify you for the mortgage loan.
Your actions after receiving lender approval for a mortgage loan can disqualify you for the loan. A mortgage loan is conditionally approved, with the lender reserving the right to re-verify credit, income, assets and employment at anytime. The lender may cancel the loan if there are any adverse changes to your qualification status.
Debt-to-Income Ratio
Your debt-to-income ratio is your gross monthly income divided by the amount you spend on debt. Debt items include mortgage payments (including principal, interest, insurance, tax), car payments, credit card payments, student loans, child support payments, etc.
The lender considers debt-to-income ratio when approving you for a mortgage loan. Only 28 percent of your income can be used for your mortgage payment, which includes taxes and insurance; and 36 percent for the mortgage payment plus the rest of your debt. Anything you do to negatively affect your debt-to-income ratio may change an “approval” to a “disqualification.”
Avoid Red Flags
A red flag is any inquiry made regarding your credit worthiness. If you decide to purchase a big ticket item – like a car, boat or furniture – prior to closing, you’re at risk of having a red flag show up on your credit report.
Keep Your Money Where It Is
The balances of your liquid assets are considered when approving you for a mortgage loan. These liquid assets may include checking accounts, savings accounts, certificates of deposit, money market accounts, retirement accounts, stock and mutual funds.
Avoid changes to the balances of these accounts. Do not close accounts. Do not change banks. A large withdrawal or deposit to any of these accounts will trigger a red flag for your mortgage lender. If a red flag is triggered, you may be asked to produce a paper trail tracking large withdrawals and/or deposits.
Employment Status
For most employees a change of jobs to one of equal or higher pay will not trigger a red flag. However, sales people should not change jobs prior to closing on their mortgage loan.
Salaried Employees
If your income is strictly salary than you should not have a problem changing to another job of equal or greater income. If, however, your income includes salary
and
bonuses, commissions and/or overtime, you should not change jobs prior to closing.
Hourly Employees
If your income is based solely on a 40-hour work week without overtime, than changing to a job with equal or greater hourly pay should not be a problem. However, if your income is dependent upon overtime pay, do not change jobs prior to closing.
Commissioned Employees
If your income is from commission or a substantial portion of your income is from commission, then you should not change jobs prior to closing. Typically, mortgage lenders average your commissions over the last two year period to determine income. Changing employers eliminates the two-year commission history and places uncertainty on your income status.
Talk to Your Loan Originator
Do not make any changes to your financial and employment status without first talking to your loan originator.
The 2013 San Diego County FHA loan limits will remain the same as 2012. The maximum loan limit will stay at $697,500 for San Diego FHA loans. FHA loans with loan amounts below $417,000 in San Diego are considered “conforming” and will have slightly lower rates and less stringent guidelines.
FHA Loans in San Diego that exceed $417,000 to the maximum of $697,500 are classified as “jumbo” or “High Balance”. San Diego High Balance FHA Loans will have slightly more restrictive guidelines and rates that are about .25% higher than the conforming loan amounts. High Balance FHA loans remain one of the few options for San Diego Mortgage Brokers to get loan amounts in the $600,000 range without going with a San Diego Jumbo Loan or a VA Loan.
The FHA loan program is a great low down payment loan option in San Diego and is used many times by First Time Homebuyers. It offers great flexibility, low rates, and an opportunity to buy a house with as little as a 3.5% down payment.
There are many other benefits to the San Diego FHA loan for borrowers. The 3.5% down payment on a purchase can be gifted to the buyer by relatives. This allows San Diego First Time Home Buyers or others who have not been able to save in today’s current economy to buy a home without having to accumulate the down payment on their own.
FHA loans in San Diego allow non-occupying co-borrowers as well. This is another great way for San Diego First Time Homebuyers to get into the housing market because parents can help them qualify for the loan. San Diego FHA loans still allows the seller to pay up to 6% of the purchase price to cover the buyer’s closing costs.
The up-front mortgage insurance premium is currently 1.75% for San Diego FHA loans, but there have been discussions that this could increase to 2.0% sometime in 2013. If you are looking to use an FHA loan to purchase a home, you may want to buy before this increase is implemented.
Please feel free to contact me if you would like to get a more information. For other California counties please see the chart below.
To get your San Diego home sold quickly, it is important that other agents in the San Diego area show it to as many potential buyers as possible. The first thing a good real estate agent will do when working with home buyers is talk to the buyer and learn what kind of San Diego home they are looking for. Then the real estate agent will search all the available San Diego homes for those most closely matching what the home buyer needs and wants. Next, the real estate agent puts together a list of the best matches to go show to that home buyer. When a busy real estate agent is compiling a list of San Diego homes to show a home buyer, the agent will naturally tend to show those houses that are easiest to gain access to first. Many San Diego homes on the market have “lock boxes” on them. The lock box is a device which holds a key to the home that only qualified local real estate agents can access. Homes that are listed as being “lock box, no appointment needed” will get shown more often than homes listed as “agent has key, call for appointment”. Why? Because they are more easily accessible and require less coordination to accomplish the showing. Accessibility is key here, no pun intended, so when possible, you should always let your real estate agent put a lock box on your home for easier showing.
If you can not do a lock box, you need to be sure that you make it as convenient and easy as possible for other San Diego agents to show your home. If they call, do whatever you have to do to accommodate letting them show your home to home buyers on their schedule. If you don’t, the real estate agent will probably show the home buyer other homes, and if that buyer makes an offer on one of them, you have just lost a great opportunity.
It is best if you can leave when the real estate agent and buyer arrive to see your home. Home buyers will not feel comfortable with you there, and it could sour an otherwise good impression of your home.

The experts all agree that curb appeal is one of the most important aspects to consider when selling your La Jolla UTC home. It is the appearance from the street that will very often determine whether potential buyers come in to see the inside, or never get out of their cars.
Flowers are one of the easiest and least expensive ways to make the front of your house look inviting and instantly increase the curb appeal of your home. Without any real landscaping at all, flowers can transform a rather drab and dreary looking front yard into one that looks colorful and lush. Especially during spring and summer, you should take advantage of the season by planting pots and flower boxes.
You should choose colorful flowers that will be in bloom during the time you are selling your home. Planting the flowers in planter boxes and pots is easier than planting them in the ground and lets you more easily place them where they can have the most visual impact. You don’t need to have a green thumb, or spend a lot of money to get great results either. Visit your local home improvement center or nursery and they will be happy to advise you of the best flowers and plants for your purpose. You can put together several very nice planter boxes and pots of flowers for well under $100. And it’s easy!
One of the nice things about using flowers in this way is that you’ll see the results immediately. And so will buyers visiting your home!
If you have any questions about how to improve the curb appeal for your home, contact Royce Kemp today for a complimentary evaluation.
Contrary to popular belief, La Jolla UTC buyers shop for homes all year round, and that includes the holiday season. In fact, if you put your home on the market during the holiday season (roughly between November and January) you may have an advantage because there are fewer houses on the local real estate market so there is less competition. With that in mind, here are five good reason to consider putting your La Jolla UTC home on the market during the holidays:
1. Home buyers looking for La Jolla UTC homes during the holidays are usually highly motivated to buy before the end of the year so they can get extra itemized income-tax deductions for mortgage loan fees, interest and pro-rated property taxes.
2. Because less savvy home sellers might postpone until Spring to sell their La Jolla UTC home, this creates a limited supply of homes on the market and gives you the opportunity to receive higher purchase offers than we might normally expect in La Jolla UTC.
3. Festive holiday lights and decorations can help your La Jolla UTC home “show better”. When home-buyers first enter your home you want to create a positive emotional experience and with a festive atmosphere you create warm feelings and attachments for the buyer, positively reinforcing their connection to your home.
4. Many home buyers have extra time off during the holiday season giving them more time to look for their new La Jolla UTC home.
5. Because January is traditionally the month for job transfers, having a home already on the market at the end of the year can attract the transferees who may not be able to wait until the Spring to purchase a La Jolla UTC home.
Copyright © 2014-2026 ROYCE KEMP. All Rights Reserved. | Sitemap | [agentimage_credits renew=true seo=true]